When people talk about financial progress, income often gets the most attention — but income alone doesn’t tell the full story of someone’s financial health. Two people earning the same salary can be in very different financial positions depending on their debts, savings, and assets. This is where net worth becomes a more complete measure of where you actually stand financially.
This guide explains what net worth is, how to calculate it, why it matters, and practical steps to improve it over time.
What Is Net Worth?
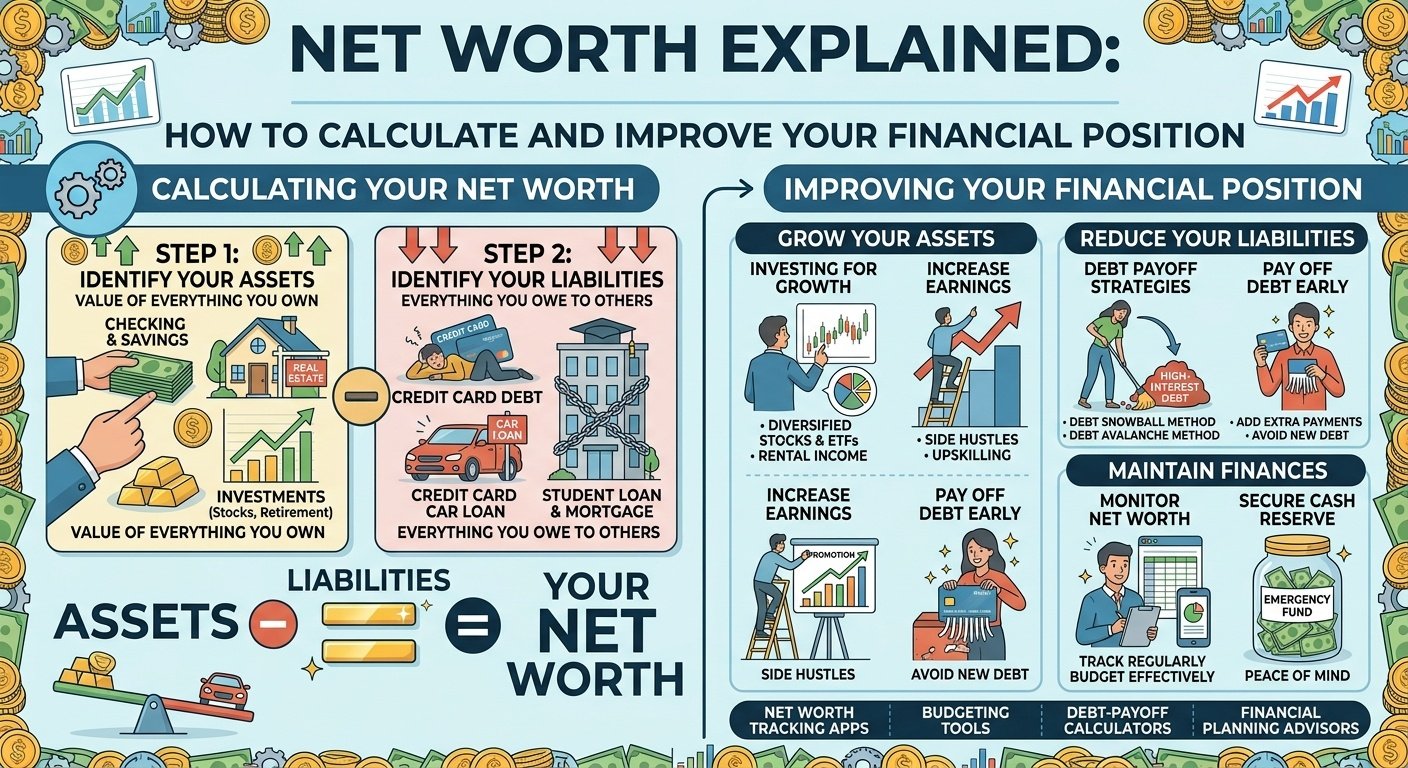
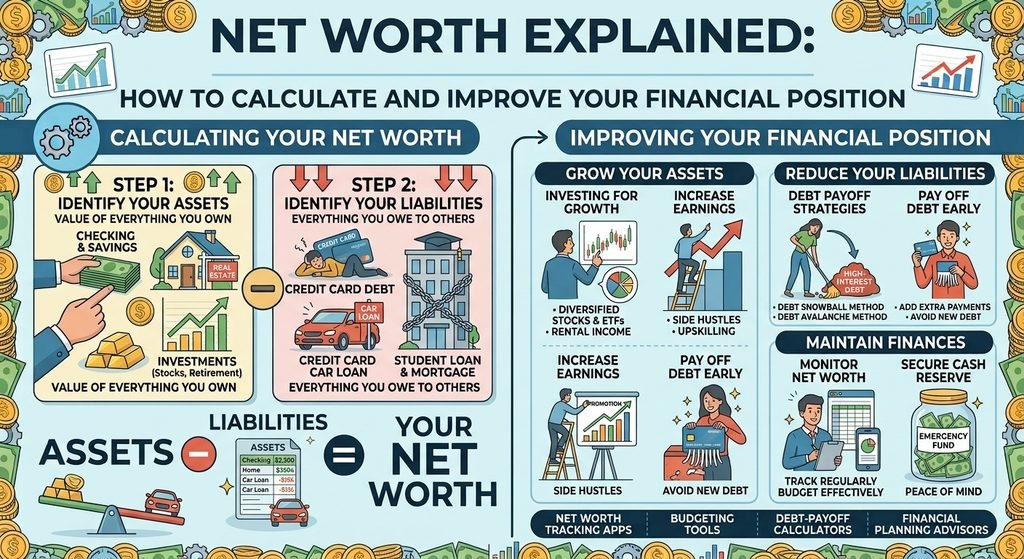
Net worth is a snapshot of your overall financial position at a given point in time. It’s calculated using a simple formula:
Net Worth = Total Assets − Total Liabilities
- Assets are things you own that have financial value, such as cash, savings, investments, or property.
- Liabilities are debts or financial obligations you owe, such as credit card balances, loans, or a mortgage.
If your assets are greater than your liabilities, you have a positive net worth. If your liabilities exceed your assets, your net worth is negative — which is common, particularly earlier in life or after taking on debt like student loans or a mortgage, and isn’t necessarily a sign of poor financial decision-making.
Why Net Worth Matters
It provides a complete financial picture. Unlike income alone, net worth accounts for both what you own and what you owe, offering a clearer view of your actual financial position.
It helps track progress over time. Calculating your net worth periodically — for example, annually — lets you see whether your financial position is improving, staying flat, or declining, regardless of short-term income fluctuations.
It supports better financial decisions. Understanding your net worth can help inform decisions about saving, debt repayment, and major purchases, by giving you a clearer sense of your overall financial capacity.
It’s a long-term measure, not a short-term one. Net worth naturally fluctuates due to market changes, new debt, or major purchases, so it’s most useful when tracked as a general trend over time rather than judged at any single moment.
How to Calculate Your Net Worth
Step 1: List Your Assets
Common categories of assets include:
- Cash and cash equivalents, such as checking and savings account balances
- Investments, including retirement accounts, brokerage accounts, and other holdings
- Real estate, such as your home’s current estimated market value
- Vehicles, generally valued at their current resale value, not the original purchase price
- Other valuable property, such as certain valuable personal items, if relevant
It’s important to use realistic, current values rather than original purchase prices, since asset values can rise or fall over time.
Step 2: List Your Liabilities
Common categories of liabilities include:
- Credit card balances
- Student loans
- Auto loans
- Mortgages
- Personal loans
- Any other outstanding debts
Use current balances rather than original loan amounts, since these decrease over time as you make payments (and can increase if additional interest or charges are added).
Step 3: Subtract Liabilities From Assets
Once you’ve totaled your assets and liabilities, subtract your total liabilities from your total assets to calculate your net worth.
A Simple Example
| Category | Amount |
|---|---|
| Checking/savings | $8,000 |
| Retirement accounts | $15,000 |
| Vehicle (current value) | $10,000 |
| Total Assets | $33,000 |
| Credit card balance | $2,000 |
| Auto loan | $7,000 |
| Student loan | $18,000 |
| Total Liabilities | $27,000 |
| Net Worth | $6,000 |
This is a simplified illustrative example — actual net worth calculations will vary widely based on individual circumstances.
Is a Negative Net Worth a Problem?
Not necessarily, especially in certain life stages. A negative net worth is common for:
- Recent graduates carrying student loan debt
- Younger individuals early in their careers, before significant savings have accumulated
- New homeowners with a large mortgage relative to their home equity
What matters more than a single snapshot is the overall trend over time. Consistent progress — reducing debt, increasing savings, and building assets — is generally a more meaningful indicator than the specific number at any one point.
How to Improve Your Net Worth
Increase Your Assets
- Save consistently, even modest, regular contributions to savings or investment accounts can add up meaningfully over time
- Invest for long-term growth, since assets like diversified investment portfolios have historically had potential to grow over long periods, though this isn’t guaranteed
- Build home equity, if applicable, by paying down mortgage principal over time
Decrease Your Liabilities
- Pay down high-interest debt, such as credit card balances, which can otherwise grow faster than many assets increase in value
- Avoid taking on unnecessary new debt, particularly for depreciating items or short-term wants
- Refinance debt when appropriate, if it genuinely reduces your interest rate or overall cost, after carefully comparing terms
Increase Your Income and Direct the Extra Toward Net Worth
Additional income, whether from a raise, side income, or other source, can accelerate net worth growth when it’s directed toward savings, investments, or debt repayment rather than increased spending.
How Often Should You Track Net Worth?
There’s no strict rule, but many people find it useful to calculate their net worth annually, or a few times a year, rather than obsessively tracking it monthly. Because asset values (like investments or real estate) can fluctuate in the short term, frequent tracking can create unnecessary stress without providing meaningful additional insight. The long-term trend is generally more informative than short-term fluctuations.
Common Mistakes When Calculating Net Worth
- Overvaluing assets, such as using original purchase prices instead of current market value
- Forgetting smaller liabilities, like outstanding medical bills or smaller personal loans
- Comparing your net worth to others, without accounting for different ages, incomes, and life circumstances
- Focusing only on the number, rather than the underlying trend over time
- Ignoring non-financial factors, such as job stability, health, or other circumstances that also affect overall financial wellbeing
Key Takeaways
- Net worth is calculated as total assets minus total liabilities, offering a broader financial picture than income alone.
- A negative net worth is common, especially earlier in life, and isn’t necessarily a sign of financial trouble.
- Tracking net worth over time, rather than focusing on a single snapshot, provides more meaningful insight into your financial progress.
- Improving net worth generally involves some combination of increasing assets, reducing liabilities, and directing additional income productively.
- Use realistic, current values for both assets and liabilities when calculating net worth.
Conclusion
Net worth offers a more complete view of your financial position than income alone, accounting for both what you own and what you owe. While a single net worth calculation is just a snapshot, tracking it over time can reveal meaningful progress and help guide better financial decisions. Whether your current net worth is positive, negative, modest, or substantial, the most important factor is consistent, intentional progress over time.